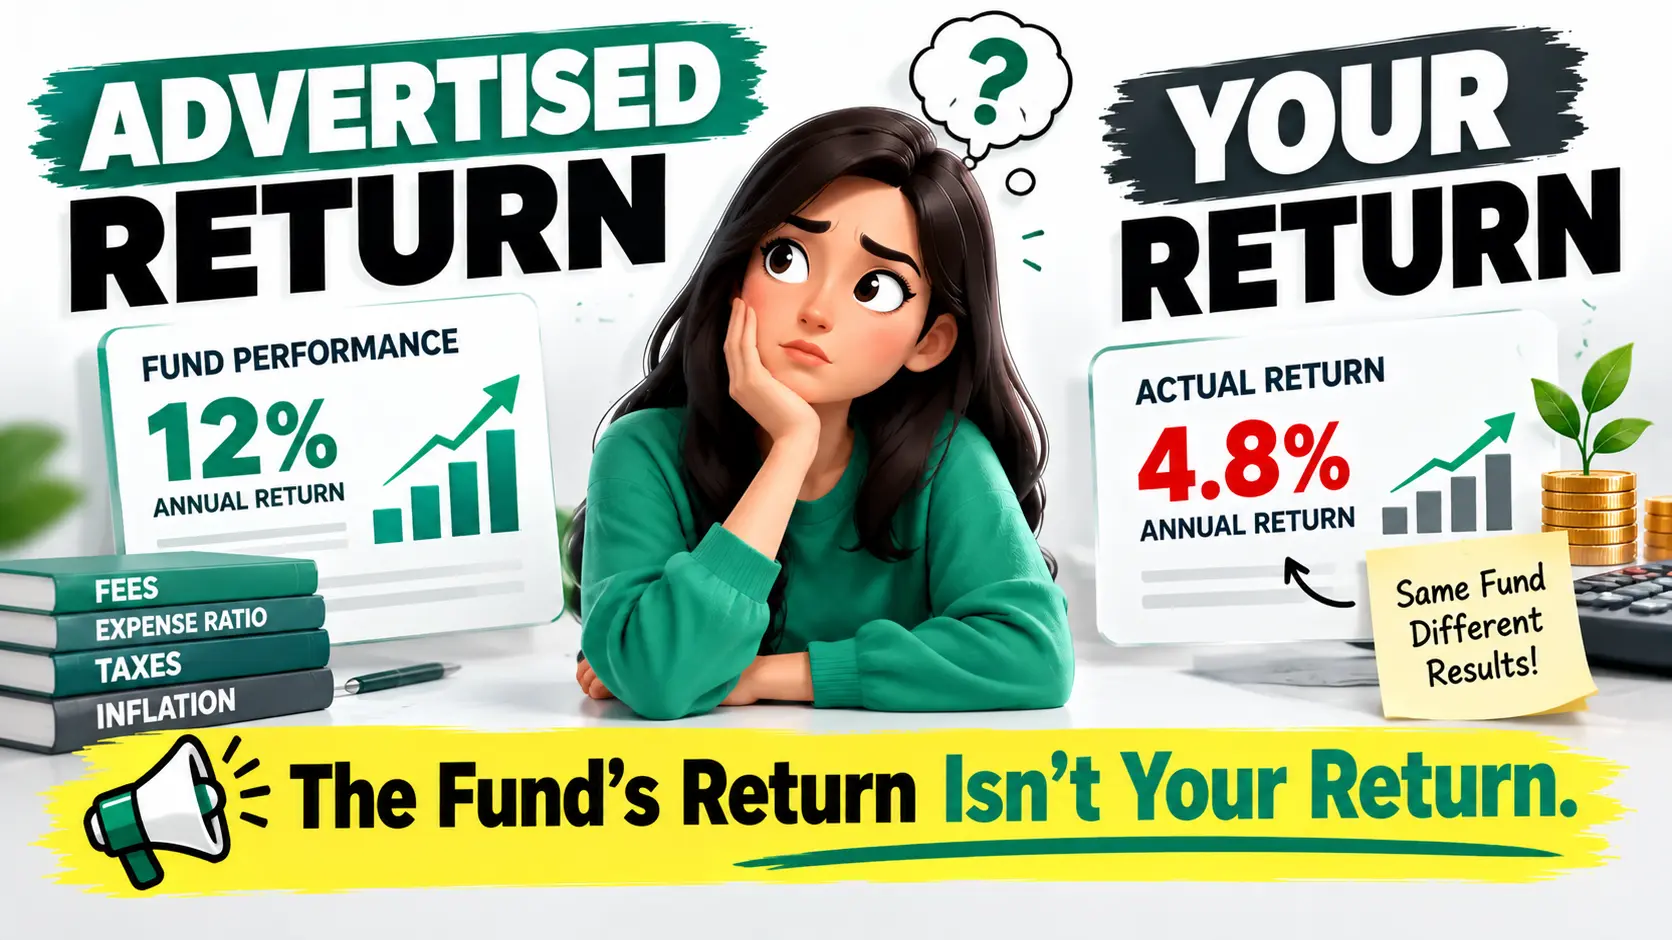
Short answer: your fund’s advertised return and the return you actually earned are two different numbers, and the gap is not the fund lying. The advertised figure, say a 5-year return of 15 percent, assumes one lump sum invested on the very first day and held the whole time. Your SIP put money in gradually, month after month, so your money was invested for different, shorter stretches. That single difference, when your money went in, is the whole reason your personal return can land above or below the advertised one. Let me show you exactly how, so you never again feel cheated by a number that is simply answering a different question.
The two returns answer two different questions
When a fund advertises a 15 percent 5-year return, it is answering: what would a person who invested one lump sum five years ago and never touched it have earned? When you look at your own statement, you are answering a completely different question: what did I earn on money I dripped in every month? Those are not the same investor, so they are not the same number. Expecting them to match is like expecting two people who boarded a train at different stations to have traveled the same distance.
What the advertised trailing return actually measures
The advertised figure is called a point-to-point or trailing return. It takes the fund’s NAV on a start date and its NAV on an end date and calculates the smooth annual growth between them:
\text{Trailing Return} = \left(\frac{\text{NAV}_{\text{end}}}{\text{NAV}_{\text{start}}}\right)^{\frac{1}{n}} - 1If the NAV went from ₹100 to about ₹201 over 5 years, that is a 15 percent annual return. But notice the hidden assumption: it counts every rupee as if it was invested on day one and rode the entire journey. That perfectly describes a one-time lump sum. It describes almost nothing about a SIP, where your rupees arrived on 60 different dates. This is the lump sum version of return, the same idea behind our lumpsum investment calculator.
What your XIRR measures
Your real return is your XIRR, the single annual rate that ties together every installment you paid, on its actual date, and the value you hold today. It solves this:
\sum_{i=1}^{N} \frac{C_i}{(1 + \text{XIRR})^{\frac{d_i - d_1}{365}}} = 0Here each C is a cash flow on its date d. Because XIRR weighs every rupee by how long it was actually invested, it reflects your experience, not a hypothetical day-one investor’s. We break down the mechanics fully in XIRR vs CAGR. The key point for now is simple: the advertised return is the fund’s headline, your XIRR is your reality, and they were never meant to be the same.
Why the gap appears, and why it swings both ways
Here is the part most articles miss. Your XIRR can be lower than the advertised return, or higher. It all depends on when the fund did its growing compared to when your money went in. In a SIP, your later installments are your biggest, because your monthly amount has been piling up, so the fund’s recent performance matters far more to you than its early performance.
| If the fund’s gains came… | Advertised 5-year return | Your likely SIP XIRR |
|---|---|---|
| Early, then flat or falling near the end | 15% | Lower, perhaps around 10% |
| Late, surging in the final year or two | 15% | Higher, perhaps around 20% |
| Steadily and evenly | 15% | Close, but usually a little lower |
Think about the first row. If the fund doubled in its first two years and then went flat, a day-one lump sum caught all of it, so the advertised return looks great. But your SIP invested most of its money during the flat years, so you missed the party and your XIRR is lower. Now the second row: if the fund did nothing for years and then surged at the end, your SIP had a large balance sitting ready to catch that surge, so your XIRR beats the advertised figure. Same fund, same period, and the timing of your cash flows decides everything. This is the same force we explore in why SIP returns look different in real life vs calculator results.
The fund isn’t lying, and the advertised number has its own quirks
None of this means the fund is deceiving you. The trailing return is a real, regulated, standardized number. But it does have a weakness worth knowing: it is extremely sensitive to the exact start and end dates. The very same fund can show an 18 percent 5-year return one month and a 9 percent 5-year return a few months later, purely because the start point shifted into or out of a crash. That is why one-line trailing returns can flatter or scare you depending on timing. A fairer way to judge a fund’s consistency is rolling returns, which test every possible start date rather than one lucky or unlucky endpoint. This endpoint sensitivity is also why a 5-year SIP can even end below cost in a bad window, as we cover in can a SIP give negative returns.
What number should you actually trust?
Use the right number for the right purpose.
- To judge your own result, use your XIRR. It is the only number that reflects your actual money and timing. Every fund app shows it, or you can calculate it yourself in a spreadsheet with the XIRR function.
- To compare funds, use rolling returns, not a single trailing number. Rolling returns show how a fund performed across many start dates, which reveals consistency instead of one flattering snapshot.
- Do not compare your SIP XIRR to a fund’s trailing return and panic. They measure different things. A lower personal number usually means the fund’s gains happened before most of your money arrived, not that anything went wrong.
- Plan with realistic assumptions. When you project a goal, use a sensible long-term rate rather than a fund’s best-ever trailing figure. Model it in our SIP calculator.
The bottom line
Your fund’s advertised return describes a day-one lump sum investor. Your XIRR describes you. The gap between them is created entirely by when your money went in, not by any dishonesty, and it can run in your favor just as easily as against it. So stop comparing the two and feeling cheated. Check your XIRR to know your true return, use rolling returns to judge a fund, and remember that in a SIP, timing of your cash flows quietly shapes the number you actually take home.
Because they measure different things. The advertised return assumes one lump sum invested on the start date and held the whole period. Your SIP invested money gradually, so each installment was invested for a different, shorter time. That timing difference, not any dishonesty, is why your personal return differs from the fund’s headline number.
A trailing or point-to-point return is the fund’s NAV growth from a start date to an end date, which suits a lump sum held the whole time. XIRR is your actual return, weighting every SIP installment by how long it was invested. The trailing return reflects a day-one investor, while XIRR reflects your real cash flows.
Yes. If the fund’s biggest gains came late, in the final year or two, your SIP had a large balance ready to catch that surge, so your XIRR can beat the advertised figure. If the gains came early instead, your XIRR is usually lower, because most of your money arrived after the big rise.
No. The advertised trailing return is a real, regulated, standardized number. It simply describes a lump sum investor, not a SIP investor. It is also sensitive to the exact start and end dates, so the same fund can show quite different trailing returns in different months, which is normal, not deceptive.
Trust your XIRR, since it is the only number that reflects your actual money and the timing of your investments. To compare funds against each other, use rolling returns rather than a single trailing figure, because rolling returns show consistency across many start dates instead of one flattering or unlucky snapshot.
Rolling returns calculate a fund’s return across every possible start date over a period, then summarize the range. This avoids the endpoint sensitivity of a single trailing return, which can look great or poor depending on one chosen date. Rolling returns give a fairer picture of how consistently a fund has performed.
